 Apparel and workwear
 Building supplies
 Medical supplies
 Fitness equipment
 Energy and power
 Industrial equipment
 Livestock supplies
 Mining supplies
 Stationery supplies
 Events and catering equipment
A South African supplier who exports goods directly, and has proof of export, can zero-rate the sale. When a foreign buyer collects goods in South Africa and takes them out, VAT is usually charged at the till and may be claimed back through the VAT Refund Administrator, if the export documents are in order.
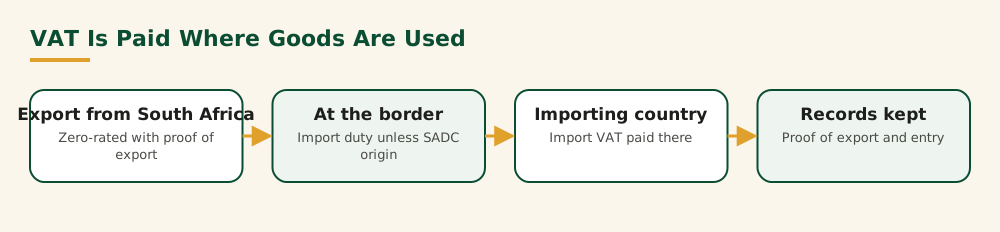
On the other side of the border, the importing country charges its own import VAT and duty. In Botswana and Namibia this is paid to BURS and NamRA at entry. In Zimbabwe and Zambia, ZIMRA and ZRA collect duty, VAT and any other levies.
The rule for traders is simple: VAT is paid where goods are used. Keep the proof of export and the import entry; without them, you may pay VAT twice.
Previous: Trade Credit, Insurance and Your Trade RecordNext: Registering and Staying Compliant