 Apparel and workwear
 Building supplies
 Medical supplies
 Fitness equipment
 Energy and power
 Industrial equipment
 Livestock supplies
 Mining supplies
 Stationery supplies
 Events and catering equipment
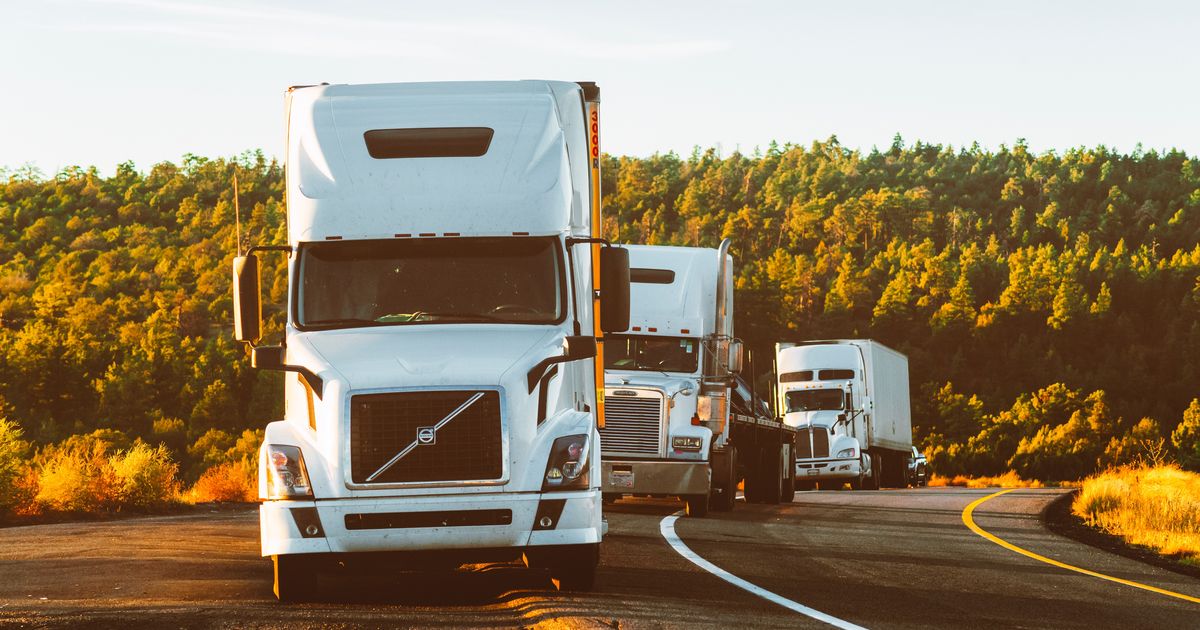
A diverse industry, investing in freight and logistics in South Africa requires an understanding of the overall industry, especially road-based. South African road-based logistics service providers are affected by consolidation processes driven by the fast-moving consumer goods sector.
Other modes of transport are still dominated by a state-owned enterprise.
The Transportation and Logistics sector is split into two parts in South Africa. Overall, the sector is dominated by Transnet, the state-owned operator and custodian of South African port, rail and pipeline infrastructure. Increased competition is now being provided by a vibrant and growing domestic road haulage and warehousing subsector. The process of consolidation has affected mainly road-based logistics service providers.
The largest of these road transport operators have grown through a process of acquiring their competitors and now command truck fleets in excess of 5,000 vehicles, excluding subcontracted fleets. This process saw the emergence of local conglomerates such as Bidvest, Imperial, Unitrans, Supergroup, Grindrod, Crossroads, Fuel Group, Value Logistics and Laser Logistics, to name some of the largest in the market. There are also about two dozen privately-owned mid-size logistics companies operating fleets of 100 to 300 trucks.
The degree of competition in the road-based logistics sector is high and has served as the primary driver of consolidation. By far the highest degree of competition exists in intermodal road haulage, containers which can easily be carried using various modes of transport, where service provision typically does not require specialised and expensive vehicles. In consequence, the barriers to entry in the intermodal road haulage business are quite low leading to depressed margins.
The intermodal road haulage market is also not based on contracts, but is rather a spot market where the lowest-cost provider typically secures the business.
Beyond intermodal road haulage, the degree of required asset specialisation has been higher, leading market players to build up their fleets along industry requirements and often also along the requirements of specific clients. In these cases, consolidation has helped service providers diversify their fleets and widen the portfolio of clients that they could effectively target.
But consolidation in the sector has not only been fuelled by the providers of logistics services. The users of such services have also integrated vertically into the transport sector by taking control of distribution centres. This is particularly the case in the fast-moving consumer goods sector. In consequence, South African logistics companies have found themselves competing not only amongst themselves, but also with their clients.
This is the first part of the article. The full article is on Cabanga Magazine, from the publishers of the regional business magazines in Africa.
Read the full article on Cabanga Magazine